
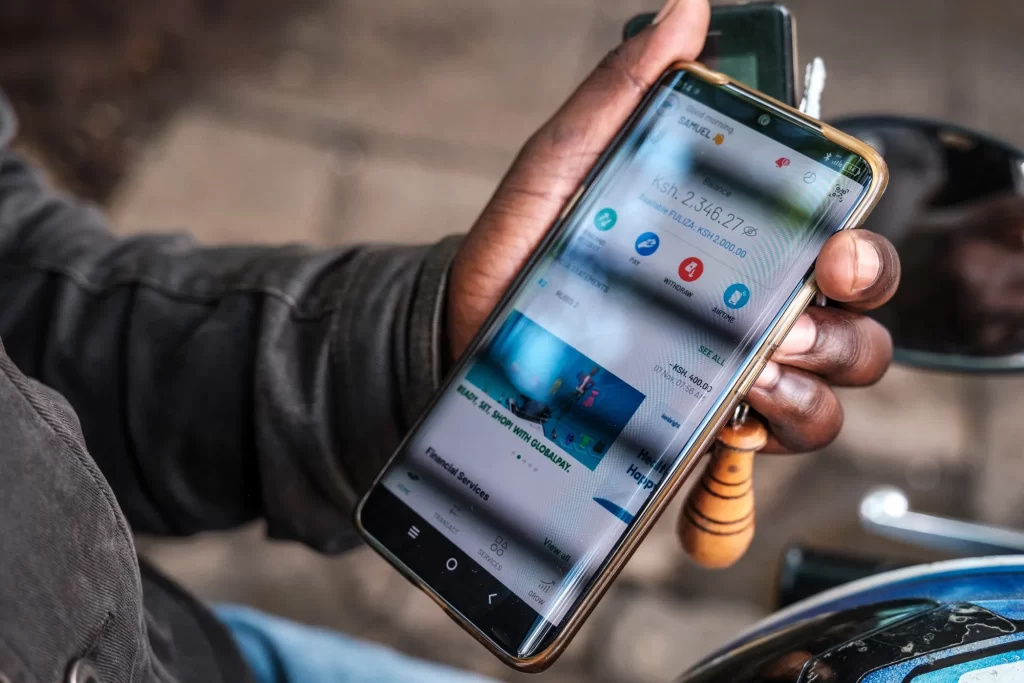
Mobile banking is central to financial life in Kenya, allowing users to send money, pay bills, and manage accounts from their phones. Despite widespread adoption, failed transactions remain common, affecting both routine payments and time-sensitive transfers.
For customers, failed mobile payments can create cash flow challenges, disrupt bill payments, and reduce confidence in digital channels. Banks face reputational risk and increased customer support costs. Analysts attribute disruptions to a combination of technical, user-related, and security factors.
Technical and System Challenges
Network connectivity is a leading cause of transaction failure, particularly in rural areas where coverage is inconsistent. Weak or dropped signals interrupt communication between users’ devices, mobile networks, and bank servers, often resulting in timeouts. Slow internet speeds can also delay processing, causing transactions to fail.
System outages, whether planned maintenance or unanticipated server failures, further affect reliability. Peak usage periods can overload networks and banking systems, creating backlogs and interruptions. Integration gaps between mobile operators and banking platforms are another factor, particularly where older banking infrastructure struggles to sync with newer technologies. Faults in APIs or software bugs introduced during app updates or new feature rollouts can also prevent payments from completing.
User-Related Causes
Insufficient funds remain a common reason for declined transactions. Payments attempted without adequate balance or exceeding daily and per-transaction limits are automatically blocked. Input errors, such as incorrect account numbers, phone numbers, or Paybill/Till numbers also contribute. Multiple failed PIN or security code attempts can lock accounts, halting further transactions.
Lack of familiarity with mobile banking procedures can exacerbate failures. First-time users may misinterpret transaction steps or security prompts, while hesitancy stemming from security concerns can result in errors that prevent successful completion.
Security and Fraud Prevention
Banks and mobile money providers implement fraud detection systems that flag unusual activity, including large sums, frequent transfers, or atypical locations. Transactions identified as potentially suspicious may be automatically declined or temporarily held for verification.
Multi-factor authentication, designed to protect accounts, can inadvertently cause failures if users do not complete steps correctly or within set timeframes. Malware and hacking attempts introduce additional risk. Malicious software can capture PINs or mimic legitimate interfaces to steal credentials, while social engineering schemes trick users into revealing sensitive information. Banks’ security measures may block these attempts but can also disrupt legitimate transactions.
Jefferson Wachira is a writer at Africa Digest News, specializing in banking and finance trends, and their impact on African economies.