
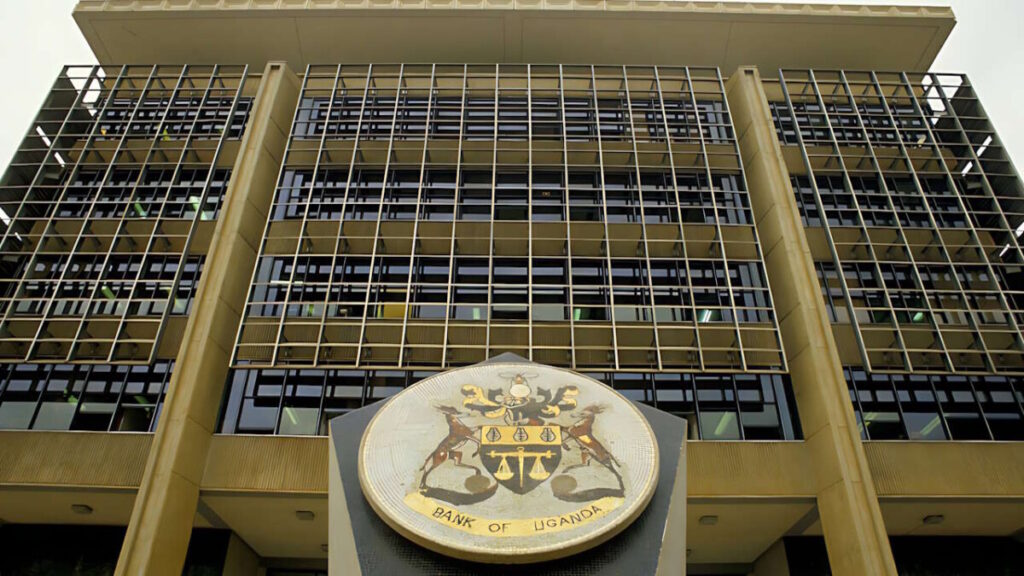
The Bank of Uganda’s Monetary Policy Committee raised its benchmark Central Bank Rate by a hefty 225 basis points to 12.0% on Tuesday, citing escalating conflict in the Middle East, a widening current account deficit, Shilling depreciation pressures and mounting inflation risks.
The decision, taken at a special meeting on October 14, 2026, lifts the rate from 9.75%. The committee also maintained the CBR band at ±2 percentage points, putting the rediscount rate at 15.0% and the bank rate at 16.0%.
Policymakers said the global economic environment had deteriorated markedly since their August meeting, driven largely by heightened geopolitical tensions in the Middle East. Those developments have disrupted shipping routes and energy infrastructure, pushed up global oil prices, raised freight and insurance costs, and fueled uncertainty in international financial markets.
“These developments have adversely affected the current account deficit and increased exchange rate volatility, intensified depreciation pressures which could amplify inflation, necessitating a tight monetary policy stance,” the committee said in its statement.
Uganda’s current account deficit has widened by $1.4 billion to $4.6 billion. The deterioration stems from lower agricultural commodity prices, particularly for coffee and cocoa, reduced tourism receipts amid temporary travel restrictions, and higher oil prices. In the 12 months to August 2026, the goods deficit worsened to $2.8 billion from $2.4 billion a year earlier.
The services deficit climbed to $3.3 billion from $2.2 billion, largely because of freight charges, while the primary income deficit rose to $1.7 billion from $1.4 billion. Secondary income, supported by higher remittances, improved to $3.1 billion from $2.7 billion.
Headline inflation rose to 4.6% in September from 4.1% in August, driven by higher food crop prices and fuel costs linked to the weaker Shilling. Core inflation has edged up more gradually, from 3.0% in May to 3.5% in August and 3.7% in September, signaling that cost pressures are beginning to broaden. Average headline and core inflation over the 12 months to September remained moderate at 3.4% and 3.3%, respectively—still below the medium-term 5% core inflation target.
The near-term inflation outlook has been revised higher. Core inflation is now projected to average 5.5–6.0% and headline inflation 7.0–7.5% over the next 12 months, reflecting rising international energy prices, exchange-rate depreciation pressures and climbing domestic food prices.
Risks to the inflation outlook remain tilted to the upside. These include further escalation of geopolitical conflicts and related jumps in energy, transport and input costs; renewed Shilling depreciation; adverse weather that hits agricultural output; and stronger domestic demand or sustained pass-through of higher fuel and food costs into core inflation and expectations. Downside risks include favorable weather boosting food supply, weaker demand and a sharper drop in international commodity prices.
Economic activity has stayed resilient but is slowing. Growth is projected at 6.4% in the quarter ending September 2026, down from 6.8% in the previous quarter. The full-year forecast for FY2026/27 has been cut to 6.0–6.5% from an earlier projection of 7.0–7.5%, reflecting tighter global and domestic financial conditions, the recent exchange-rate depreciation, and the impact of elevated energy prices and geopolitical uncertainty.
Over the medium term, growth is still expected to strengthen to an average of about 8%, supported by private investment, stronger exports, oil-sector developments and the government’s Tenfold Growth Strategy.
Growth risks are skewed to the downside, including persistent high energy and transport costs, prolonged geopolitical and trade disruptions, adverse weather and tighter-than-expected financial conditions.
In September the central bank had already raised the Cash Reserve Requirement to 13.5% from 11% to curb excess liquidity and strengthen policy transmission. Tuesday’s rate hike aims to contain inflationary pressures, limit second-round effects from higher energy prices and currency depreciation, and anchor inflation expectations around the medium-term target.
“The MPC will continue to assess domestic and global economic developments and stand ready to take additional measures, as warranted, to preserve price and financial stability,” the committee said.