
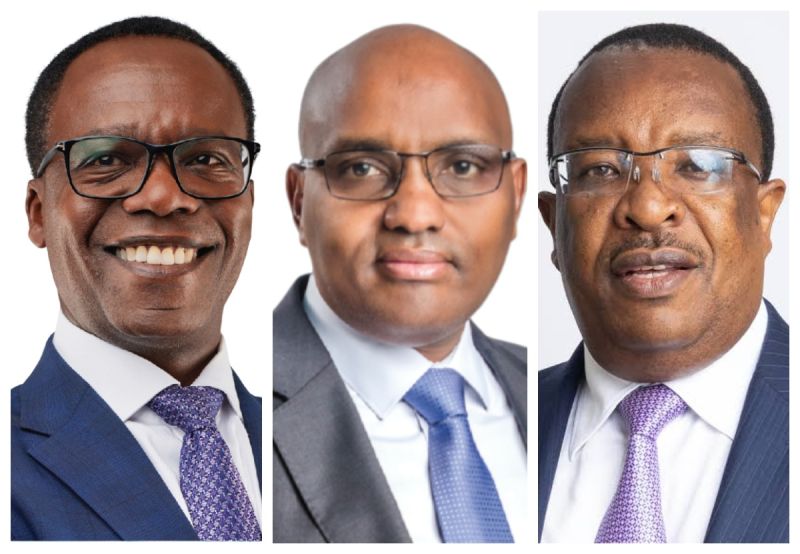
The prosecution of the chief executives of Co-operative Bank, KCB Group and NCBA Group over alleged failure to report suspicious transactions linked to a Sh363.4 million fraud case has been temporarily halted after the banks and their executives moved to the High Court to challenge the proceedings.
The three bank executives have been accused of failing to report suspected proceeds of crime under Section 5 as read with Section 44(2) of the Proceeds of Crime and Anti-Money Laundering Act (POCAMLA).
However, the applications filed by Co-operative Bank and NCBA have resulted in interim orders preventing the arrest, arraignment and prosecution of the affected executives while the High Court considers their cases.
The orders provide an early indication of the central issue being contested by the banks: whether the criminal proceedings against their executives should proceed over transactions that prosecutors allege should have triggered suspicious transaction reporting obligations.
The case arises from allegations that Sh363.4 million was stolen from First Assurance Investment Company Limited between May 2018 and April 2024 through transactions involving accounts held at Co-operative Bank, KCB Bank and NCBA Bank.
The CEOs are not accused of stealing the Sh363 million
One of the key distinctions in the case is between the alleged theft of funds and the charges facing the bank executives.
The prosecution has separately charged former nominated MCA Salim Mohamed Busaidy with allegedly stealing Sh363,420,459 from First Assurance Investment Company between May 18, 2018 and April 30, 2024.
Busaidy has been accused of using his position as a director and his access to the company’s bank accounts at the three banks to withdraw company funds.
The DPP approved 120 charges against him, including three counts of conspiracy to defraud, two counts of stealing, 114 counts of making a document without authority and one count of acquisition of proceeds of crime.
The prosecution alleges that Busaidy forged the signature of his co-director, Lamu Governor Issa Abdalla Issa, on company cheques and used the documents to facilitate withdrawals.
The bank executives, however, face a different allegation. The DPP has accused the executives of failing to report suspected proceeds of crime under POCAMLA.
This places the conduct attributed to the CEOs in a different category from the alleged theft itself. The prosecution case against them concerns what the banks and their officers allegedly knew or should have identified from the transactions and whether that information should have been reported to the Financial Reporting Centre.
The banks are challenging the criminal proceedings
Co-operative Bank has obtained interim High Court orders stopping the prosecution of the bank and its CEO, Dr Gideon Muriuki, in relation to the First Assurance Investment Company matter.
The bank’s application was placed before Justice Gregory Mutai, who on August 7, 2026, certified the Notice of Motion dated August 6 as urgent and admitted it for hearing during the court recess.
The court then issued interim conservatory orders restraining the respondents from arresting, presenting for plea taking, charging or prosecuting the petitioners in Milimani Chief Magistrate’s Court Criminal Case Number E451 of 2026, Republic v Salim Mohammed Busaidy & 6 Others. The order also covers other criminal proceedings arising from the investigations against the petitioners.
The High Court further stayed proceedings in the criminal case pending the inter partes hearing of the application. The orders do not determine the underlying criminal allegations. Instead, they preserve the position of the parties while the High Court considers the application.
The matter will be mentioned on October 12, 2026, to ascertain compliance and for further directions.
NCBA challenges prosecution of John Gachora
NCBA Group has taken a similar position in relation to its Group CEO John Gachora. The bank obtained High Court orders stopping proceedings against the bank and Gachora over allegations relating to the failure to report suspicious transactions involving a director of an investment company.
NCBA’s application resulted in conservatory orders staying further proceedings in Criminal Case Number E451 of 2026 pending the inter partes hearing and determination of the application.
The High Court also issued a prohibitory order preventing the first and second respondents from arresting, arraigning, instituting, maintaining or continuing criminal proceedings against the first petitioner or any officer of the second petitioner arising from the case.
A separate order barred the relevant Magistrate’s Court from taking the petitioner’s plea, hearing or determining the criminal case pending the High Court proceedings. The NCBA application is scheduled for further directions on August 27, 2026.
The central question is the reporting obligation
The prosecution’s case against the executives is based on the requirements imposed on financial institutions under POCAMLA. Section 44 requires financial institutions to monitor transactions that are unusual, complex, large or inconsistent with a customer’s known activities.
Where a financial institution suspects that funds may be connected to criminal activity, the law requires the suspicious activity to be reported to the Financial Reporting Centre. The prosecution’s position is that the transactions involving First Assurance Investment Company’s accounts should have raised suspicion and triggered reporting obligations.
The alleged transactions took place over several years and involved multiple withdrawals. According to the prosecution, the transactions eventually resulted in the loss of more than Sh363 million from the company.
The DCI has also alleged that some of the funds were subsequently used to acquire luxury vehicles and other personal assets. The prosecution therefore links the CEOs to the matter through the alleged failure to identify and report suspicious transactions, rather than alleging that they personally participated in the theft.
What the banks’ court applications seek to establish
From the interim orders, the immediate objective of the banks and executives is to prevent the criminal proceedings from continuing while the High Court considers their applications. Co-operative Bank’s application seeks protection from arrest, plea taking, charging and prosecution arising from the impugned investigations.
NCBA’s application similarly seeks to prevent arrest and criminal proceedings against the bank and its officers in connection with the same criminal case.
The applications therefore challenge the basis for subjecting the bank and its executives to the criminal process before the High Court has determined the issues raised in their petitions and applications.
The orders also prevent the Magistrate’s Court from progressing with the criminal case against the affected petitioners while the High Court applications remain pending. The court has required the respondents and interested parties to respond to the applications before the matters proceed to further directions.
The prosecution must connect the transactions to a failure to report
The allegations against the Co-op, KCB and NCBA CEOs depend on the reporting obligations under POCAMLA. The prosecution alleges that the transactions were sufficiently suspicious that the financial institutions should have identified and reported them.
That position will have to be considered alongside the banks’ challenge to the criminal proceedings.
The material provided does not set out the full grounds contained in the banks’ petitions or applications. It therefore does not establish, at this stage, the precise legal arguments the banks will advance on issues such as the application of Section 44, the evidence supporting the alleged reporting failure, or the individual responsibility of the CEOs.
What is established from the court orders is that the banks and executives have asked the High Court to intervene before the criminal proceedings against them continue.
A separate case remains against Busaidy
The criminal allegations against Busaidy remain separate from the proceedings challenging the prosecution of the bank executives. Busaidy denied the 120 charges before Chief Magistrate Gethi Kibiru and was released on a Sh10 million bond with one surety of a similar amount or a cash bail of Sh3 million.
The prosecution alleges that he used access to First Assurance Investment Company’s accounts at Co-operative Bank, KCB Bank and NCBA Bank to make withdrawals using forged cheques. The alleged transactions covered the period from May 2018 to April 2024.
The prosecution further alleges that Busaidy acquired Sh363,320,459 knowing that the money represented proceeds of crime arising from the alleged theft.
The case against the bank executives is connected to those transactions through the separate allegation that the financial institutions failed to report suspected proceeds of crime.
High Court intervention now separates the two proceedings
The August 7 orders have temporarily separated the prosecution of the bank executives from the progress of the criminal case while the High Court considers their applications.
For Co-operative Bank and Dr Gideon Muriuki, the next key date is October 12, when the High Court is scheduled to ascertain compliance and issue further directions. For NCBA and John Gachora, the matter is scheduled for mention on August 27 for further directions.
The interim orders do not determine whether the allegations against the bank executives are proved. They prevent their prosecution and stay the relevant proceedings pending the hearing and determination of the applications before the High Court.
The central dispute is therefore whether the alleged transactions created a reporting obligation under Kenya’s anti-money laundering law and whether the criminal proceedings against the banks and their executives should proceed on that basis.